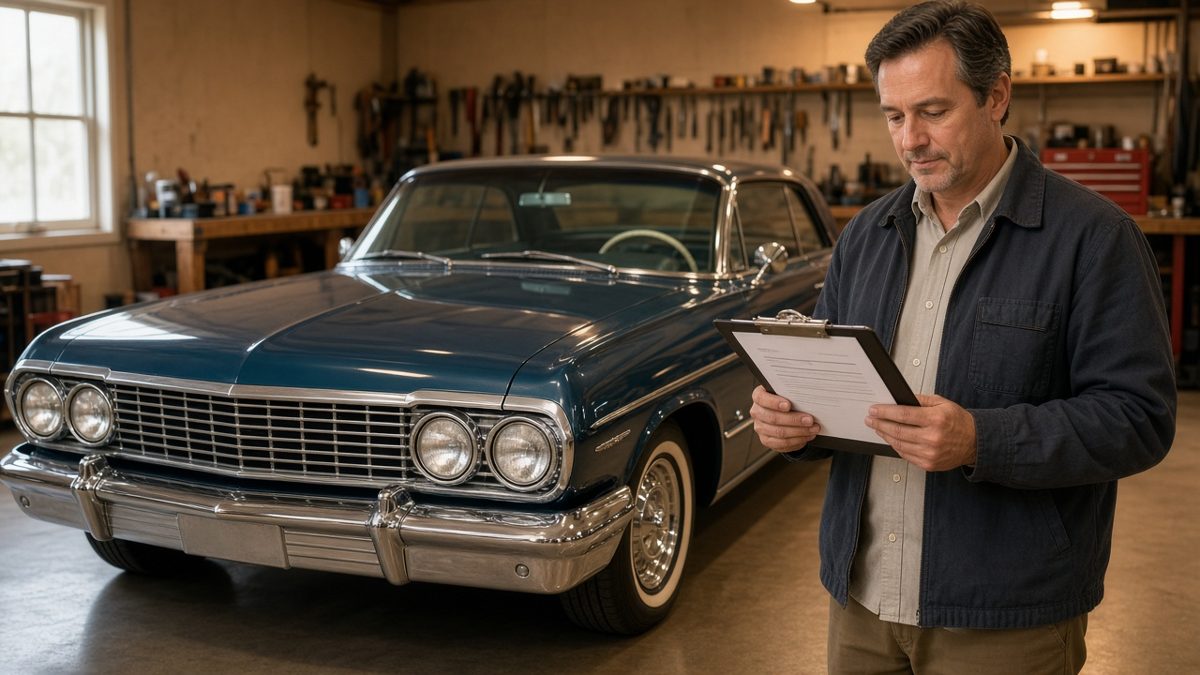
A classic or collectible car is not just transportation. It may represent years of restoration work and a value that rises rather than falls over time. A standard auto policy is built for everyday vehicles that depreciate, so it may pay far less than a collector car is worth after a total loss. Classic car insurance is designed for vehicles that are driven occasionally and valued for their collectibility. This guide explains how it works, who qualifies, and what to compare.
How classic car insurance differs from standard auto insurance
Valuation
The most important difference is how the car is valued.
- Actual cash value (ACV). Standard policies usually pay the vehicle’s market value at the time of loss, which accounts for depreciation. For an older car, ACV formulas may produce a low figure that does not reflect collector demand or restoration quality.
- Agreed value. Most classic car policies use agreed value: you and the insurer agree on the car’s value when the policy is written, often supported by photos, appraisals, or sales data. If the car is a total loss, the insurer pays that amount, minus any deductible if applicable.
- Stated value. Some policies use stated value, which sounds similar but typically pays the lesser of the stated amount or actual cash value. Read policy language carefully.
Usage restrictions
Classic car policies assume limited, pleasure use. They commonly restrict the car to car shows, club events, parades, and occasional drives. Commuting, running errands, or business use are often excluded.
Lower premiums
Because collector cars are usually driven less and cared for carefully, classic car premiums are often lower than standard coverage on a comparable vehicle, though pricing depends on the insurer, the car, and the driver.
Typical eligibility requirements
Each insurer sets its own rules, but common requirements include:
- Vehicle age. Many insurers define classics as at least 20 or 25 years old, while antiques may be 45 years or older. Some insure newer exotic or limited-production cars as collectibles.
- Condition. The car generally must be maintained or restored, not a daily beater.
- Storage. A locked, enclosed garage or similar secure storage is often required.
- Mileage limits. Plans may offer annual mileage tiers, such as 2,500 or 5,000 miles, while some offer flexible or unlimited pleasure use.
- Daily driver. You usually must own another vehicle for regular use, insured under a standard policy, for each licensed driver in the household.
- Driving record. Insurers may require a clean record and a minimum driver age or experience.
What classic car policies cover
Like standard auto insurance, classic policies typically include:
- Liability for injuries and property damage you cause, subject to state minimums
- Collision for damage from accidents
- Comprehensive for theft, fire, vandalism, weather, and animal strikes
- Uninsured and underinsured motorist coverage
- Medical payments or personal injury protection depending on the state
Specialized coverages
Many collector policies offer options not common on standard policies:
- Spare parts coverage for parts stored separately
- Restoration coverage for cars under repair, sometimes with values that increase as work progresses
- Inflation guard that raises the agreed value automatically over time
- Flatbed towing to avoid damage from conventional towing
- Choice of repair shop, including specialists in classic vehicles
- Event or show coverage for trips to car shows
- Diminished value or salvage rights options allowing you to keep a damaged vehicle
What affects premiums
- Agreed value: higher values mean higher premiums
- Make, model, and rarity
- Mileage plan you choose
- Storage location and security
- Your driving history and claims record
- Deductible amount
- Location, including theft rates and weather risks
Establishing the right agreed value
Underinsuring a classic leaves you short after a loss, while overinsuring wastes premium because the insurer typically pays the agreed value, not more. To set an accurate value:
- Get a professional appraisal, especially for rare or highly restored cars.
- Review recent sales of comparable vehicles in similar condition at auctions and through dealers.
- Use valuation guides focused on collector cars.
- Document the car with photos, receipts, and restoration records.
- Review the value annually and adjust as the market or condition changes.
Common exclusions and pitfalls
- Using the car for commuting or errands, which may violate policy terms
- Exceeding mileage limits without notifying the insurer
- Allowing unlisted drivers to operate the car
- Storing the car outdoors when the policy requires enclosed storage
- Wear and tear, mechanical breakdown, and rust, which are typically not covered
- Racing or track events unless specifically endorsed
Classic car insurance vs. a standard policy
| Feature | Classic car policy | Standard auto policy |
|---|---|---|
| Valuation | Usually agreed value | Usually actual cash value |
| Use | Limited pleasure use | Unrestricted personal use |
| Premium | Often lower for low-mileage collectibles | Based on daily driving risk |
| Specialty options | Spare parts, restoration, flatbed towing | Limited |
| Eligibility | Age, storage, daily driver requirements | Broad |
If you drive an older car every day, a standard policy may be the only option. If the car is a cherished collectible used occasionally, a classic policy usually provides better protection.
How to shop
Compare several specialty insurers and standard carriers that offer collector programs. Ask each:
- Is coverage agreed value or stated value?
- What mileage options are available?
- What are the storage and daily-driver requirements?
- Is there coverage for spare parts and restoration?
- Can I choose my repair shop?
- Does the policy include roadside assistance with flatbed towing?
Insuring a car during restoration
Many collector cars spend months or years in a shop. A standard policy may not fit a car that cannot be driven, and some owners drop coverage entirely, leaving the car exposed to fire, theft, or damage at the shop. Specialty insurers often offer restoration or “under construction” coverage that insures the car’s current value and increases the coverage limit as work is completed and documented. Keep receipts and progress photos to support value increases, and confirm whether the shop carries garagekeepers coverage for customer vehicles in its care.
Insuring multiple collector cars
Collectors with several vehicles may be able to insure them on one policy with a single mileage plan or discounted pricing for additional cars. Some insurers also cover collectible motorcycles, trucks, and military vehicles. Ask whether each car needs its own agreed value and whether storage requirements apply to every vehicle. If you lend a car for a show or museum display, confirm that coverage continues while the car is away from your garage and in transit.
State registration considerations
Many states offer antique or historic plates for older vehicles, often with lower registration fees but with restrictions on use. These state designations are separate from insurance eligibility, but their usage limits can overlap with your policy’s limits. Check both before driving.
Documentation to keep
Store copies of your appraisal, purchase records, restoration invoices, and dated photographs of the car from several angles, including the engine bay, interior, and undercarriage. Keep a copy off site or in cloud storage so it survives a fire or theft that destroys the car. Good documentation speeds up claims and supports the agreed value if it is ever questioned.
Related reading: Pet Insurance Explained: How Policies Pay, What They Exclude, and Whether It Pays Off and GAP Insurance for Cars: When You Need It, Where to Buy It, and How Claims Are Paid.
Frequently Asked Questions
What is agreed value coverage?
It is a valuation method in which you and the insurer agree on the car’s value up front, and that amount is paid if the car is a total loss.
How old does a car need to be for classic car insurance?
Many insurers require 20 to 25 years, though some insure newer collectible or exotic cars.
Can I drive my classic car every day?
Generally no. Most classic policies limit use to pleasure driving and exclude commuting.
Is classic car insurance cheaper?
It is often cheaper than standard coverage for low-mileage collectible vehicles, but pricing varies.
What is the difference between agreed value and stated value?
Agreed value pays the agreed amount after a total loss, while stated value often pays the lesser of the stated amount or actual cash value.
This article is for general informational purposes only and is not legal, medical, tax, or financial advice. Rules vary by state and change over time; confirm details with the relevant agency or a licensed professional.