If you own your car outright and need money quickly, a car title loan can seem like an easy solution. Lenders often approve borrowers with poor credit in less than an hour, and you keep driving the car while you repay. The trade-off is steep. Title loans typically carry very high fees, many borrowers roll them over repeatedly, and failing to pay can cost you your vehicle, which may be how you get to work. This guide explains how car title loans work, what they cost, what the law allows, and the alternatives that may meet your needs for far less risk.
What a car title loan is
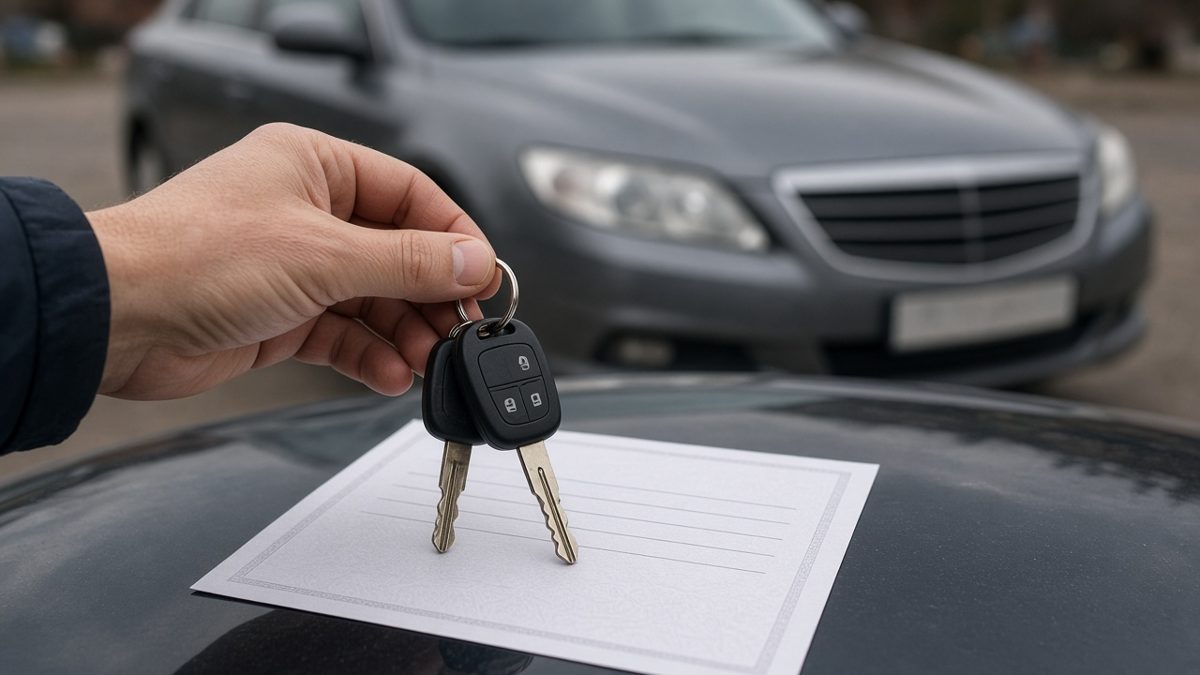
A car title loan, also called an auto title loan, is a short-term secured loan that uses your vehicle’s title as collateral. You give the lender the title, and the lender places a lien on the vehicle. In return, you receive cash, usually a fraction of the car’s value. Some lenders also install GPS trackers or starter interrupt devices, or keep a spare key.
Single-payment title loans are generally due in about 30 days, with the principal and fee due in one lump sum. Some states allow installment title loans repaid over several months.
How much title loans cost
Title lenders commonly charge a monthly fee expressed as a percentage of the loan. The Consumer Financial Protection Bureau has reported that a fee of about 25% per month is typical, which equals an APR of roughly 300%.
Example
You borrow $1,000 against your car with a 25% monthly fee.
- Fee for 30 days: $250
- Amount due in 30 days: $1,250
- Equivalent APR: about 300%
If you cannot repay $1,250 and roll the loan over, you pay another $250 fee and still owe $1,000. After four months of rollovers, you would have paid $1,000 in fees and still owe the full principal.
Additional costs may include lien fees, processing or document fees, roadside assistance add-ons, and repossession or storage fees if you default.
The rollover and repossession risk
The CFPB’s research on single-payment auto title loans found that most loans were reborrowed, with many borrowers stuck in long sequences of loans, and that about one in five borrowers who took out a single-payment title loan had their vehicle repossessed.
Repossession can lead to:
- Losing transportation to work, school, or medical appointments
- Repossession, towing, and storage fees
- Sale of the vehicle at auction, sometimes for less than its value
- In some states, owing a deficiency balance if the sale does not cover the debt, while other states require lenders to return any surplus
State laws vary widely
Title lending is regulated by states:
- Some states prohibit title loans or cap interest rates at levels, often 36% APR, that make typical title loans impractical.
- Some states permit them with limits, such as maximum loan amounts, rate caps, limits on rollovers, required repayment plans, or rules on repossession notices and surplus returns.
- Some states have few restrictions.
Licensed lenders must follow the rules of the state where you live. Check your state attorney general’s or financial regulator’s website to see whether title loans are legal and whether a lender is licensed. Online lenders may claim exemption from state law; be cautious.
Military protections
Under the Military Lending Act, active-duty service members and their dependents are protected by a 36% cap on the military annual percentage rate for most consumer credit, and lenders generally cannot take a vehicle title as security on covered loans.
Who uses title loans and why
Title loans appeal to people who need cash fast and have limited access to credit, perhaps because of low credit scores or no bank account. Common reasons include rent, utility bills, car repairs, and medical expenses. But because the loan must usually be repaid in a lump sum from the same tight budget, the cycle of reborrowing is common.
Safer alternatives
Credit union payday alternative loans
Federal credit unions offer payday alternative loans with APRs capped at 28%, amounts from $200 to $2,000, and terms of one to 12 months. Many credit unions also offer small personal loans and emergency loans.
Personal installment loans
Banks, credit unions, and online lenders offer personal loans with fixed payments. Even loans for fair or poor credit typically cost far less than title loans and do not put your car at risk.
Negotiating with creditors
Utilities, hospitals, landlords, and lenders often offer hardship programs or payment plans. Ask before borrowing.
Employer help
Some employers offer paycheck advances, earned wage access, or emergency assistance funds.
Local and government assistance
Community action agencies, 211 referral lines, charities, and religious organizations may help with rent, utilities, food, and car repairs. The Low Income Home Energy Assistance Program helps eligible households with energy bills.
Selling unused items or side income
Selling items you do not need or taking on temporary work can raise cash without debt.
Credit counseling
A nonprofit credit counseling agency can help build a budget and, if needed, a debt management plan.
Warning signs of a problem lender
Be cautious if a lender pressures you to borrow more than you need, does not clearly state the fee and APR in writing, asks you to sign a blank or incomplete contract, or refuses to explain what happens if you miss a payment. Lenders that are not licensed in your state, that demand upfront fees before funding, or that ask for your online banking password are red flags. Federal Truth in Lending rules require lenders to disclose the finance charge and APR before you sign, so compare those figures carefully and walk away if they are missing.
If you already have a title loan
- Read your contract to understand the fee, due date, and what happens if you miss a payment.
- Ask about installment or repayment plans, which some states require.
- Pay more than the fee whenever possible to reduce the principal.
- Refinance with a cheaper loan, such as a credit union loan, to pay off the title loan.
- Know your rights in repossession. Many states require notice before sale and the right to redeem the car by paying the balance. Some require the lender to return any surplus from the sale.
- File complaints about abusive practices with your state regulator and the CFPB.
Title loans vs. other options
| Option | Typical cost | Collateral | Risk |
|---|---|---|---|
| Car title loan | About 300% APR | Your vehicle | Repossession |
| Payday loan | Near 400% APR | Bank account access | Fees and overdrafts |
| Credit union PAL | Up to 28% APR | None | Low |
| Personal loan | Varies by credit | Usually none | Moderate |
| Credit card cash advance | Fee plus high APR | None | Revolving debt |
Building protection for the future
An emergency fund, even a small one, is the best defense against needing a title loan. Automating small transfers from each paycheck into savings can build a cushion. Improving your credit over time with on-time payments can also open cheaper options when emergencies happen.
Related reading: Credit Utilization Ratio: How Card Balances Move Your Score and How to Manage Them.
Frequently Asked Questions
How does a car title loan work?
You give the lender your car title as collateral and receive cash, usually a fraction of the car’s value. You keep driving the car but must repay the loan and fee, typically within 30 days, or risk repossession.
How much does a title loan cost?
Fees around 25% per month are typical, which equals an APR of about 300%. A $1,000 loan could cost $250 in fees for one month.
Can a title lender take my car?
Yes. If you default, the lender can repossess and sell your vehicle, subject to your state’s rules on notice, redemption, and any surplus from the sale.
Are title loans legal in every state?
No. Some states prohibit them or cap rates at levels that make them impractical, while others allow them with varying limits.
Does a title loan affect my credit score?
Many title lenders do not check credit or report on-time payments, but defaults sent to collections can be reported and hurt your credit.
This article is for general informational purposes only and is not legal, medical, tax, or financial advice. Rules vary by state and change over time; confirm details with the relevant agency or a licensed professional.