Car registration, holiday gifts, annual insurance premiums, a new laptop, and back-to-school clothes rarely arrive as true surprises. Yet many budgets treat them as emergencies because the money is not set aside when the bill shows up. A sinking fund solves that problem by spreading a known future cost across the months before it is due. This guide explains how sinking funds work, how to set them up, and how to keep them running smoothly.
What a sinking fund is
A sinking fund is money you save gradually for a specific, planned expense. The term comes from corporate finance, where companies set aside money to repay bonds over time. In personal finance, it simply means dividing a future cost by the number of months until it is due and saving that amount each month.
A simple example
Your car insurance renews every six months at $720. Instead of finding $720 at once, you save $120 a month. When the bill arrives, the money is ready and your monthly budget is undisturbed.
Sinking funds vs an emergency fund
Both are savings, but they serve different purposes:
| Feature | Sinking fund | Emergency fund |
|---|---|---|
| Purpose | Known or likely expenses | Unexpected events, such as job loss or major medical bills |
| Timing | Often predictable | Unpredictable |
| Spending | Planned and expected | Used only when necessary |
| Size | Based on specific goals | Often several months of essential expenses |
Without sinking funds, people often dip into their emergency fund for predictable costs, leaving less protection for real emergencies.
Choosing your sinking fund categories
Start by reviewing the last 12 months of bank and card statements to find irregular expenses. Common categories include:
- Vehicle costs: registration, maintenance, tires, insurance premiums paid annually or semiannually
- Home costs: repairs, appliance replacement, HOA special assessments, property taxes not paid through escrow
- Medical costs: deductibles, dental work, glasses, and contact lenses
- Holidays and gifts: birthdays, weddings, and seasonal celebrations
- Travel: vacations or trips to see family
- Education: school supplies, activity fees, and tuition payments
- Technology: replacing phones and computers
- Pets: annual vet visits and boarding
- Subscriptions and memberships: annual software, warehouse clubs, and professional dues
You do not need all of these. Pick the five to eight that most often disrupt your budget.
How to calculate monthly contributions
Use this formula for each category:
Target amount ÷ months until needed = monthly contribution
If you want $1,200 for holiday spending and it is 10 months away, save $120 a month. For costs without a fixed date, such as car repairs, estimate an annual amount from past spending and divide by 12.
Prioritize when money is tight
If the total feels overwhelming, rank funds by urgency and consequences. Insurance premiums and taxes come before vacations. You can start with smaller contributions and raise them as other debts are paid off.
Where to keep sinking fund money
High-yield savings accounts
Online banks and credit unions often pay higher interest than traditional savings accounts. Look for FDIC or NCUA insurance, no monthly fees, and easy transfers.
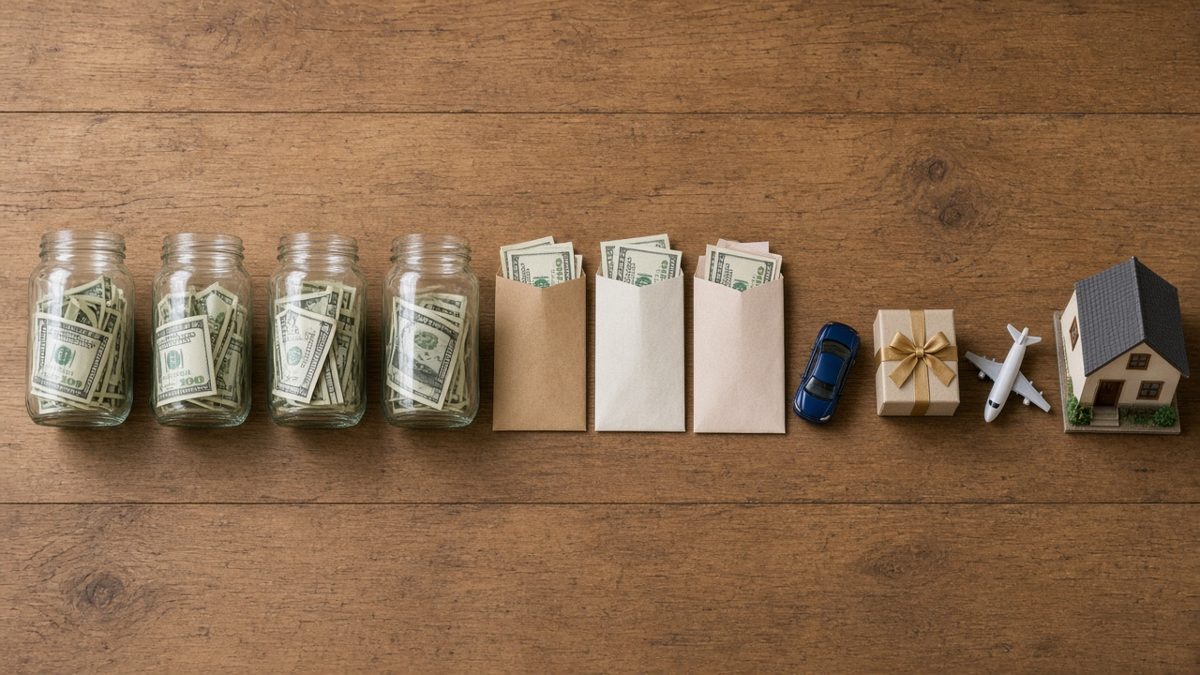
Multiple accounts or “buckets”
Some banks let you create sub-accounts or savings goals within one account, each with its own name. Seeing “Car Repairs: $640” helps you avoid spending money meant for something else.
Single account with a tracker
Others keep all sinking funds in one savings account and use a spreadsheet or budgeting app to track each category’s balance. This works well if you are disciplined about updating records.
Short-term certificates of deposit
For a large, fixed future cost, such as tuition due in nine months, a CD with a matching term can earn a guaranteed rate. Early withdrawal penalties make CDs less suitable for uncertain timing.
Automating your sinking funds
Automation makes saving effortless:
- Schedule a transfer from checking to savings right after each payday.
- Split the transfer among categories based on your plan.
- Review balances monthly and adjust amounts after big purchases.
Automatic transfers prevent the common problem of good intentions fading after a few months.
Using a sinking fund when the bill arrives
When the expense comes due, pay from checking and transfer the matching amount from the sinking fund. Some people pay with a credit card for rewards and then use the sinking fund to pay the statement in full. Either method works as long as the money is used for its intended purpose.
If costs exceed your fund
If a repair costs more than you saved, cover the difference from flexible budget categories or, if necessary, your emergency fund. Then increase that sinking fund’s monthly contribution so you are better prepared next time.
Common mistakes to avoid
- Too many categories. Twenty small funds can become hard to manage. Combine related costs.
- Underestimating costs. Use actual past spending and allow for inflation.
- Borrowing between funds without a plan. Moving money from the vacation fund to cover car repairs is fine if you rebuild it.
- Keeping funds in checking. Money in the same account as daily spending is easy to spend by accident.
How sinking funds fit into budgeting methods
Sinking funds work with almost any budget. In zero-based budgeting, contributions get their own line items. In percentage-based approaches, sinking funds often fit within the savings or needs portion depending on the category. The key is that irregular costs become regular monthly line items.
A sample sinking fund plan for one year
Here is how a household might organize a year of irregular costs. Suppose their review of last year’s statements found these expenses: $1,440 for semiannual car insurance, $600 for vehicle maintenance and tires, $900 for holiday gifts, $1,800 for a summer family trip, $480 for annual software and memberships, and $1,200 for home repairs. The total is $6,420, or $535 a month.
If $535 feels too large at first, the household can rank the categories. Car insurance is mandatory and arrives on a fixed date, so it gets fully funded at $240 a month. Maintenance and home repairs are likely but uncertain, so they start at $100 combined. Gifts and travel are flexible, so the family funds them at a lower level and adjusts the size of the trip to match what they actually saved. Software memberships get reviewed, and any that are no longer used are canceled instead of funded.
After three months, they compare actual spending with the plan. If a car repair used most of the maintenance fund, they raise that contribution slightly and trim the travel fund for a few months. This kind of regular check-in keeps the system realistic. Over time, the household stops treating predictable costs as emergencies, uses credit cards only for convenience rather than to bridge gaps, and finds that its emergency fund stays intact for real surprises.
Related reading: Credit Utilization Ratio: How Card Balances Move Your Score and How to Manage Them and Series I Savings Bonds: How I Bond Rates Work and When to Buy.
Frequently Asked Questions
How many sinking funds should I have?
There is no set number. Most households do well with five to eight categories covering their most common irregular expenses.
Should I build an emergency fund or sinking funds first?
Many people start with a small starter emergency fund, then add sinking funds for predictable expenses, and continue growing the emergency fund over time.
Can sinking funds earn interest?
Yes. Keeping them in a high-yield savings account, money market account, or short-term CD can earn interest while keeping the money accessible.
Are sinking funds only for big purchases?
No. They work for any predictable expense, from a $60 annual subscription to a $4,000 roof repair reserve.
What if I need to use a sinking fund early?
Use it if needed, then adjust your plan by increasing contributions or pushing back the target date to rebuild the balance.
Do sinking funds work for couples with separate finances?
Yes. Couples can keep a shared sinking fund for joint costs, such as home repairs or family trips, and individual funds for personal expenses. Agree on how much each person contributes, often in proportion to income, and review balances together every few months.
This article is for general informational purposes only and is not legal, medical, tax, or financial advice. Rules vary by state and change over time; confirm details with the relevant agency or a licensed professional.